2025 Blueprint: Analyzing the Global Housing Market and Emerging Real Estate Trends
As a real estate analyst who has spent the last decade navigating market cycles, analyzing development pipelines, and advising on portfolio allocations, I can tell you that the rules of the game are fundamentally shifting. The global housing market in 2025 is no longer just about location, location, location. It is a complex matrix of demographic pressures, strict environmental regulations, volatile mortgage rates, and urgent government interventions.
Currently, global demand for new housing construction sits at 53.0 million units in 2025. Looking ahead, we are forecasting a 2.7% compound annual growth rate (CAGR), pushing that figure to 60.7 million units by 2030. This growth within the global housing market is not uniform. It is being heavily spurred by chronic housing shortages in developing nations, while mature economies are wrestling with aging infrastructure, affordability crises, and the transition toward sustainable building practices.
In this comprehensive analysis, we will break down the regional dynamics, shifting asset classes, and high-level macroeconomic factors that are actively reshaping the global housing market today, providing a strategic roadmap for developers, investors, and industry professionals.
The North American Pivot: Single-Family Dominance and the Sun Belt Migration
In the United States and Canada, the global housing market is experiencing a distinct structural pivot. For the past decade, high-density urban multifamily projects were the darlings of real estate investment portfolios. Today, the narrative has flipped. We are seeing a massive resurgence in single-family housing demand, driven largely by aging millennials who are finally entering their peak homebuying years and seeking more space.
This demographic wave is colliding with improved income conditions for certain segments of the workforce, pushing demand out of hyper-expensive coastal metros and into lower-cost exurban areas and the Sun Belt. Cities like Austin, Miami, Phoenix, and Charlotte are seeing sustained new housing construction because land is more readily available and local zoning regulations are often more accommodating.
From a developer’s perspective, the math on multifamily has become exceedingly difficult. High vacancy rates in certain urban pockets, combined with restrictive commercial lending environments and mounting construction costs, have compressed profit margins. Single-family builds—particularly build-to-rent (BTR) communities—are far more attractive right now. They require lower upfront capital, offer faster turnaround times, and are highly appealing to institutional investors utilizing advanced property management software to scale their portfolios efficiently. Furthermore, homeowners in these regions are increasingly tapping into home equity loans to fund renovations, recognizing that upgrading their current footprint is often more cost-effective than navigating the current high-interest-rate environment.
Asia-Pacific: Navigating Oversupply and Government Stimulus
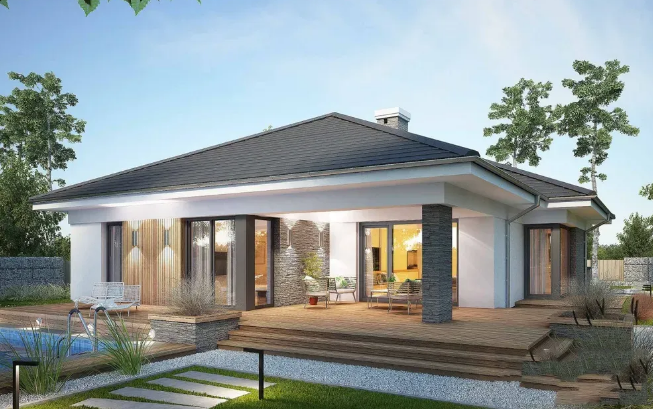
You cannot discuss the global housing market without deeply analyzing the Asia-Pacific region, and more specifically, China. The Chinese real estate sector has served as a cautionary tale over the past few years. Rapid, speculative building led to a massive oversupply of housing in small and lower-tier cities, which ultimately triggered a real estate bubble. In response, regulators tightened lending restrictions, causing significant financial instability for heavily leveraged developers.
However, the tide is beginning to turn. Policy support is poised to revitalize China’s housing market, with a strategic shift away from speculative sprawl and toward targeted growth in key urban centers. The government is heavily backing large-scale affordable housing initiatives and urban renewal projects. These government-backed housing efforts are crucial for absorbing excess inventory while providing modern, safe living conditions for the urban workforce.
Across the broader Asia-Pacific region, the contrast within the global housing market is incredibly sharp. In advanced economies like Japan and South Korea, an aging population dictates a need for accessible, technology-integrated homes. Meanwhile, in emerging markets like India, Indonesia, and the Philippines, rapid urbanization is fueling intense demand for high-density new housing construction. Governments across these nations are stepping in to formalize informal settlements, utilizing public-private partnerships to upgrade the housing stock and meet the overwhelming demand for basic shelter.
Europe’s Dual Narrative: Western Sustainability and Eastern Constraints
The European sector of the global housing market is a tale of two distinct realities. In Western Europe, the market is entirely dominated by the push for energy efficiency and climate compliance. The housing stock in countries like Germany, France, and the UK is notably old, with a vast majority of homes built before 1980. This aging infrastructure is driving massive demand for retrofitting and upgrades in energy efficiency, smart home technology, and modern design.
For new housing construction, demand for low-carbon, sustainable building practices is reshaping the landscape. Driven by aggressive European Union climate goals and increasingly strict building codes, developers are pivoting heavily toward sustainable materials and passive house designs. Urban infill and redevelopment projects are gaining tremendous traction as cities face severe land scarcity. Municipalities are desperate to increase housing density near transit corridors, employment centers, and revitalized industrial zones. To offset severe labor shortages and manage ballooning timelines, developers are increasingly turning to modular and off-site construction methods. These modern construction techniques reduce waste, lower carbon footprints, and allow for rapid assembly on-site.
Conversely, Eastern Europe faces a much more constrained environment within the global housing market. The legacy of Soviet-era apartment blocks presents an enormous renovation challenge, complicated by highly fragmented ownership structures and broader demographic declines. Furthermore, new housing construction in this region is being heavily suppressed by stubborn inflation, severe labor shortages, and weak consumer confidence. While there is a clear need to modernize the housing stock, the macroeconomic headwinds make real estate investment in Eastern European residential development highly speculative at this moment.
Emerging Markets: Middle-Class Expansion and Climate Resilience
When we look at Central and South America, as well as the Africa and Middle East regions, we see the most aggressive growth vectors in the global housing market. Across Central and South America, new housing construction is being propelled by a burgeoning middle class and relentless internal migration from rural areas to urban centers. However, a significant portion of the existing housing stock in this region remains informal or self-built, suffering from severe infrastructure deficits.
What is particularly notable in Latin America is the shift toward climate resilience. As extreme weather events become more frequent, new housing projects are increasingly focused on flood-resilient designs and sustainable infrastructure. Affordability remains the highest hurdle, but innovative micro-finance models and targeted government subsidies are beginning to bridge the gap.
In Africa and the Middle East, surging population growth and massive urban expansion are fueling unprecedented demand. In cities spanning from Lagos to Riyadh, large-scale affordable housing initiatives are taking root. The Middle East, in particular, is heavily investing in heat-ready designs and master-planned communities that integrate commercial real estate, retail, and residential spaces into cohesive, tech-enabled smart cities. Substandard dwellings remain a critical issue across much of Africa, but international real estate investment and government partnerships are slowly working to formalize the housing stock and provide adequate shelter to millions of new urbanites.
The Transformation of the Existing Housing Stock
To truly understand the global housing market, one must look beyond new builds and analyze the existing global housing stock. The disparities in quality, formality, and readiness for future challenges are staggering.
Historically, tracking from 2015 to our current 2025 data, we see that single-family detached homes still dominate the North American landscape, representing the bulk of existing residential floor space. In contrast, high-density rental housing characterizes the vast majority of Western Europe’s housing stock.
The global housing market is currently facing an aging crisis. Millions of units across North America and Europe require immediate modernization to meet modern safety and environmental standards. This is creating a lucrative sub-sector for contractors, building material suppliers, and specialized real estate investment trusts (REITs) focused on value-add renovations. Investors are closely monitoring mortgage rates and property valuations to identify older, multi-family assets that can be acquired, green-retrofitted, and repositioned in the market for higher yields.
Modern Construction Methods and PropTech Integration
Labor shortages are a universal pain point in the global housing market. From the exurbs of Texas to the urban core of London, developers cannot find enough skilled tradespeople to meet the 53.0 million unit demand. This bottleneck is accelerating the adoption of modular and off-site construction methods. By moving the bulk of the building process onto climate-controlled factory floors, developers can control costs, reduce material waste, and drastically cut down on project timelines.
Furthermore, technology is revolutionizing how we interact with the global housing market. Property management software has evolved from simple rent-collection tools into robust, AI-driven platforms that manage predictive maintenance, tenant screening, and energy consumption across massive portfolios. For institutional investors managing thousands of single-family rental units, these software solutions are not just conveniences; they are critical infrastructure that dictates the profitability of their real estate investments.
Macroeconomic Factors and the Investment Outlook
Operating within the global housing market requires a keen eye on macroeconomic indicators. Over the last few years, central banks worldwide have engaged in aggressive monetary tightening to combat inflation. The resulting spike in mortgage rates temporarily froze market liquidity, leaving many prospective buyers sidelined and forcing developers to hit pause on capital-intensive multifamily projects.
However, as we look toward the 2030 forecast, we anticipate a stabilization in global gross domestic product (GDP) and a gradual easing of lending restrictions. Capital is already beginning to flow back into the residential sector, but it is highly targeted. Investors are prioritizing markets with strong employment growth, favorable tax environments, and proactive local governments.
In the commercial real estate sector, the lingering effects of remote work have battered traditional office valuations. As a result, savvy developers are actively exploring adaptive reuse projects—converting vacant office towers in central business districts into mixed-use residential spaces. While the plumbing and zoning challenges are immense, these conversions represent a creative solution to urban housing shortages and a unique opportunity within the global housing market.
Looking Ahead to 2035: The Future of Global Residential Construction
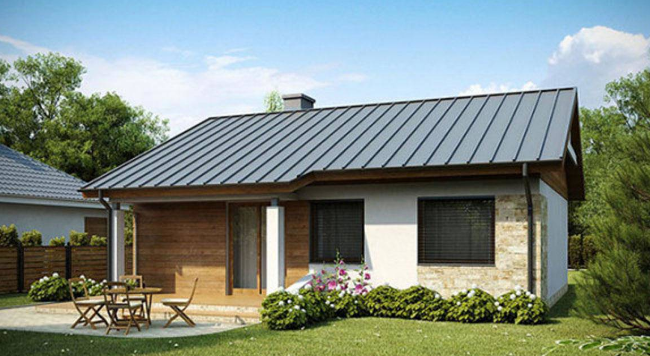
The trajectory of the global housing market from 2025 to 2035 will be defined by adaptation. Climate change is no longer an abstract concept; it is actively dictating where homes can be insured and how they must be built. Governments will be forced to take an even heavier hand in the market, utilizing a mix of strict regulations, tax incentives, and direct subsidies to reduce housing deficits and ensure equitable access to shelter.
Demographics will continue to be the ultimate arbiter of demand. The aging populations of Eastern Europe and Japan will require housing that supports aging-in-place, heavily reliant on smart-home healthcare integrations. Conversely, the youth bulges in Africa and Southeast Asia will require rapid, scalable, and affordable housing solutions that prioritize density and basic infrastructure.
The global housing market is vast, encompassing everything from luxury single-family estates in North America to micro-apartments in Asian megacities. Yet, despite this extreme divergence in pace and structure, the underlying themes remain identical across borders: the urgent, undeniable need for resilient, efficient, and inclusive housing stock that can seamlessly accommodate the rapidly changing social and environmental realities of the 21st century.
Whether you are a local developer looking to capitalize on Sun Belt migration, an institutional investor leveraging property management software for a build-to-rent portfolio, or a policy maker structuring affordable housing initiatives, the data is clear. The demand for well-constructed, strategically located housing will only intensify over the next decade.
If you are looking to position your portfolio ahead of these macroeconomic shifts or need deep-dive data on specific regional forecasts, now is the time to refine your strategy. Connect with our advisory team today to access our full proprietary data sets, interactive regional mapping, and customized real estate investment consulting tailored for the 2025-2030 cycle.