The 2025 Global Housing Market: Real Estate Trends, Regional Forecasts, and Investment Strategies
Over the past decade that I have spent analyzing property cycles and real estate investment trends, few periods have presented as complex a landscape as the current global housing market. We are navigating an era where shifting demographic sands, stringent environmental regulations, and macroeconomic headwinds are forcing developers, investors, and policymakers to completely rewrite their playbooks. As we move deeper into 2025, the global housing market is not just expanding; it is undergoing a profound structural evolution.
At present, demand for new residential construction across the global housing market has reached an impressive 53.0 million units in 2025. Based on current economic trajectories and property development pipelines, this figure is forecast to grow at a compound annual growth rate (CAGR) of 2.7%, pushing total new deliveries to approximately 60.7 million units by 2030. This growth within the global housing market is being predominantly fueled by chronic, systemic housing shortages in developing nations, alongside an urgent need to modernize aging residential infrastructure in established Western economies.
For anyone involved in real estate asset management, residential property development, or institutional real estate investment, understanding the nuanced regional dynamics of the global housing market is no longer optional—it is critical for survival and portfolio profitability.
North America: The Single-Family Resurgence and the Sun Belt Boom
When we analyze the North American sector of the global housing market, the narrative is heavily dictated by changing consumer life stages and a recalibration of capital deployment. For years, high-density urban multifamily projects were the darling of commercial real estate developers. However, the current environment—characterized by elevated mortgage rates, tighter credit facilities, and stubbornly high construction costs—has noticeably cooled the urban multifamily sector.
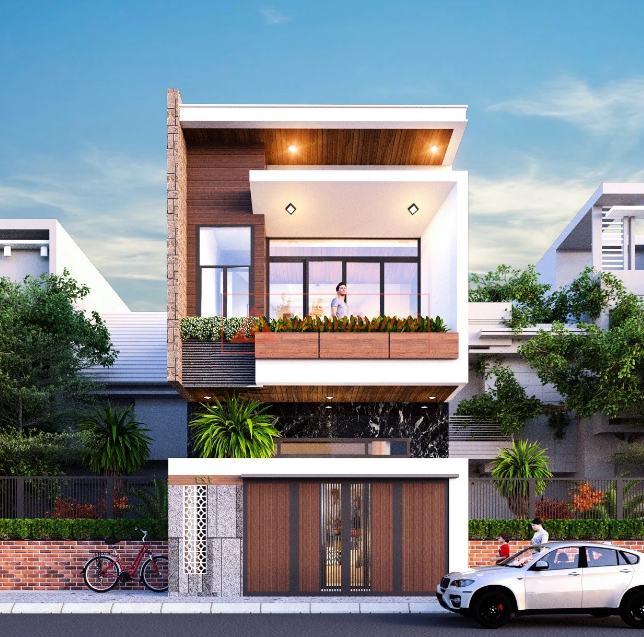
Instead, we are witnessing a massive pivot toward lower-density, single-family residential projects. Aging millennials are now squarely in their peak homebuying and family-forming years. Coupled with stabilized income conditions and a widespread acceptance of remote or hybrid work models, this demographic is driving robust demand in exurban areas and the Sun Belt.
Local search intent data and regional property transactions reveal a stark contrast in geographic performance. For instance, the traditional housing market in New York and the high-density urban cores of Los Angeles real estate are experiencing rising vacancy rates in older multifamily assets. Conversely, we are seeing aggressive expansion in real estate services in Texas, as well as rampant Miami property development. Developers in these lower-cost, land-rich regions are finding single-family build-to-rent (BTR) communities highly attractive due to faster turnaround times, lower upfront capital requirements, and accelerated leasing velocities compared to sprawling multifamily mid-rises. In this corner of the global housing market, the smart money is heavily weighting suburban single-family portfolios.
China’s Market Correction and the Asia-Pacific Growth Engine
You cannot discuss the global housing market without addressing the elephant in the room: China. For much of the 21st century, China was the undisputed heavyweight champion of new housing construction. Today, it serves as a cautionary tale of over-leverage and speculative excess. The Chinese real estate bubble has resulted in a massive oversupply of residential units, particularly in Tier 3 and Tier 4 cities.
Consequently, Chinese lending institutions have become hyper-restrictive, cutting off the easy capital that once fueled rampant speculation. However, the narrative is not entirely bleak. We are seeing heavy policy support poised to revitalize specific segments of China’s housing market. The government has pivoted away from unchecked sprawl, heavily promoting large-scale affordable housing initiatives and targeted urban renewal projects. This strategic shift is expected to stabilize new construction volumes in vital tier-one urban centers, ultimately preventing a hard landing for the broader Asian sector of the global housing market.
Beyond China, the wider Asia-Pacific region is a hotbed of real estate investment activity. Rapid urbanization, a burgeoning middle class, and aggressive government-backed housing efforts are driving immense construction volumes. Countries like India and Vietnam are experiencing a surge in demand for both single-family and multifamily housing, requiring innovative property management software and advanced real estate services to handle the unprecedented scale of new urban developments.
Western Europe: Pioneering Sustainable Building Practices
In Western Europe, the global housing market is entirely intertwined with the push toward decarbonization. European developers are operating under some of the most stringent environmental, social, and governance (ESG) mandates in the world. Driven by aggressive EU climate goals and strict updated building codes, demand for energy-efficient housing has fundamentally reshaped the property development landscape.
Unlike the sprawling subdivisions of North America, Western Europe faces severe land scarcity. Consequently, the European slice of the global housing market is heavily characterized by high-density rental housing and urban infill projects. Developers are focusing intensely on redeveloping revitalized industrial zones and increasing housing density near established transit corridors.
For real estate asset management firms operating in this region, the primary challenge—and opportunity—lies in the existing housing stock. A vast majority of European homes were built prior to 1980. The massive capital expenditure required to retrofit these older assets with sustainable building practices, smart grid integrations, and low-carbon heating systems represents one of the highest-yield real estate investment opportunities of the decade. Those who can efficiently modernize legacy portfolios will dominate this segment of the global housing market.
Eastern Europe: Navigating Demographic Declines and Renovation Needs
Moving to Eastern Europe, the dynamics of the global housing market shift drastically. This region is currently grappling with a triad of headwinds: persistent localized inflation, severe skilled labor shortages, and generally weak consumer confidence. Furthermore, the region is facing a demographic decline, which naturally depresses the organic demand for net-new single-family housing units.
However, the legacy of Soviet-era block housing presents a massive, unavoidable need for renovation. The existing residential floor space in Eastern Europe requires significant modernization. Progress here is often complicated by highly fragmented property ownership structures, making large-scale block renovations legally and financially complex. Despite these hurdles, targeted real estate investment in modernization and energy-efficiency upgrades remains a high-priority sector within this localized tier of the global housing market.
Central and South America: The Rise of Climate-Resilient Urbanization
In Central and South America, the global housing market is being propelled forward by internal migration from rural areas to urban centers, alongside a steadily expanding middle class. However, this rapid urbanization has historically resulted in high levels of informal, self-built housing stock that suffers from severe infrastructure deficits.
Today, institutional property development in the region is increasingly focused on formalizing these settlements through public-private partnerships. Furthermore, climate vulnerability is a pressing reality. From coastal flooding to extreme weather events, new housing construction in South America is rapidly adopting climate-resilient designs. Affordable housing initiatives here are no longer just about providing shelter; they are about providing safe, durable infrastructure that can withstand the environmental realities of 2025 and beyond. For high-net-worth investors monitoring the global housing market, South American infrastructure-integrated real estate offers attractive, high-growth emerging market exposure.
Africa and the Middle East: Demographic Booms and Mega-Projects
Nowhere is the raw, quantitative demand for new construction more evident than in Africa and the Middle East. This sector of the global housing market is being supercharged by explosive population growth and some of the highest urbanization rates on the planet.
In the Middle East, high-CPC commercial real estate trends often highlight luxury developments, but the real volume lies in master-planned communities designed to house growing local populations and expatriate workforces. Heat-ready designs and advanced water conservation technologies are standard requirements for new builds in this arid region.
Meanwhile, across the African continent, the sheer volume of the housing deficit is staggering. Substandard dwellings remain widespread, but a wave of large-scale affordable housing initiatives is beginning to take root. Governments from Nigeria to Kenya are actively seeking foreign direct real estate investment to fund massive residential projects. Because of the vast scale required, this region of the global housing market is ripe for disruption by innovative construction technologies that can deliver standardized housing units at an unprecedented pace.
Overcoming Global Bottlenecks: PropTech and Modular Construction Methods
Across every region of the global housing market, from the bustling housing market in New York to the expanding suburbs of Manila, developers share a common set of operational bottlenecks: severe labor shortages, unpredictable supply chain disruptions, and the rising cost of raw materials.
To maintain margins and meet the forecasted demand of 60.7 million new units by 2030, the real estate industry is undergoing a technological renaissance. Modular and off-site construction methods have transitioned from niche experimental concepts to mainstream industry standards. By moving the bulk of the construction process to controlled factory environments, property developers can drastically reduce build times, minimize material waste, and bypass the localized lack of skilled on-site labor. This shift is particularly accelerating in Western Europe and advanced Asian economies, where labor costs represent a disproportionate share of total development expenses.
Furthermore, the integration of advanced PropTech (Property Technology) is optimizing how the global housing market functions. From property management software that streamlines tenant relations in sprawling multifamily portfolios, to AI-driven real estate asset management platforms that predict localized housing demand, technology is the great enabler of this decade’s real estate investment strategies.
Future-Proofing Your Real Estate Investment Strategy
Having monitored these cycles for a decade, my advice to developers, private equity firms, and individual investors is clear: the global housing market of 2025 rewards precision over broad speculation. The days of indiscriminate land banking and guaranteed double-digit equity returns on standard multifamily builds are behind us.
To generate alpha in today’s global housing market, capital must be aligned with the undeniable macro trends. First, prioritize energy-efficient housing and sustainable building practices. Not only are regulatory bodies mandating it, but end-users are increasingly demanding it, resulting in noticeable green premiums on asset valuations.
Second, pay attention to demographic migration. The localized demand spikes in areas experiencing corporate relocations—such as the surge in real estate services in Texas and Miami property development—will consistently outperform legacy urban centers burdened by aging infrastructure and high taxation.
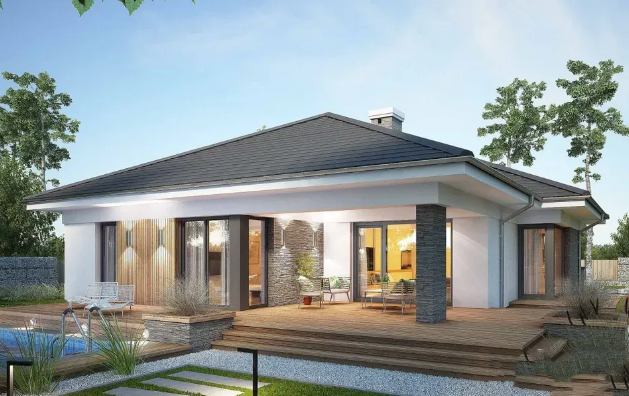
Finally, embrace alternative construction methods. Developers who master modular construction methods will effectively insulate themselves from the volatility of traditional labor markets, ensuring project delivery on time and under budget. The global housing market will always have cyclical ups and downs, but the structural deficit of quality, affordable, and sustainable homes provides a massive, multi-decade runway for strategic real estate investment.
The Road Ahead for the Global Housing Market
As we look toward 2030 and 2035, the global housing market will continue to diverge in its localized execution, yet remain unified by common global challenges. Aging populations in Japan and Eastern Europe will dictate specialized senior living developments, while the youthful, hyper-growth cities of Africa will demand rapid, scalable affordable housing initiatives.
Whether we are tracking the resurgence of single-family homes in North America, the policy-driven stabilization of China’s real estate bubble, or the ESG-compliant redevelopment of Western Europe, the core mandate remains the same: the world needs resilient, efficient, and inclusive housing stock.
Understanding the intricacies of the global housing market is the first step toward capitalizing on these generation-defining shifts. If you are an investor, developer, or industry professional looking to optimize your portfolio and stay ahead of the evolving real estate investment landscape, it is time to turn these insights into actionable strategies. Connect with our expert real estate advisory team today to explore deep-dive analytics, high-yield property development opportunities, and bespoke market forecasts tailored to your specific investment goals. Let’s build the future of your real estate portfolio, together.