The 2025 Global Housing Market Forecast: Real Estate Investment, Regional Shifts, and Construction Trends
As a real estate analyst and industry consultant with over a decade in the trenches, I’ve watched the global housing market navigate through financial crashes, pandemic-induced booms, and drastic supply chain disruptions. Today, as we look at the data shaping 2025 and beyond, it is abundantly clear that the global housing market is undergoing a massive structural transformation. Driven by shifting demographics, volatile mortgage rates, and aggressive climate policies, the global housing market is rewriting its own rules.
Currently, global demand for new housing stands at an impressive 53.0 million units in 2025. Projections indicate a steady 2.7% compound annual growth rate (CAGR), pushing that figure to 60.7 million units by 2030. This expansion is heavily spurred by chronic housing shortages in rapidly developing nations, alongside an urgent need to modernize the aging housing stock in mature economies. Whether you are heavily involved in real estate investment, managing property development portfolios, or navigating commercial real estate loans, understanding these macro and micro shifts is no longer optional—it is critical for survival and growth.
The Macro Drivers Reshaping the Global Housing Market
To truly grasp the trajectory of the global housing market, we must first look at the foundational elements driving new construction and existing property renovations. Across the board, we are seeing a fascinating intersection of demographic pressure and economic reality.
One of the most pressing challenges across the global housing market is the persistent labor shortage. The days of relying on an endlessly expanding pool of cheap construction labor are over. Consequently, modular construction and off-site building methods are rapidly transitioning from niche alternatives to mainstream solutions. By shifting construction to controlled factory environments, developers can mitigate the impact of labor shortages, reduce material waste, and tightly manage project timelines.
Simultaneously, sustainable building practices are commanding a premium in the global housing market. We are transitioning into an era where energy-efficient housing is not just a consumer preference but a strict regulatory requirement. From sophisticated property management software tracking energy usage to the rising demand for ESG-compliant (Environmental, Social, and Governance) real estate investment trusts (REITs), the global housing market is inextricably linked to global climate goals.
Asia/Pacific: The China Rebalance and Regional Urbanization
You cannot accurately analyze the global housing market without taking a magnifying glass to the Asia/Pacific region, and more specifically, China. For years, China’s hyper-accelerated building boom drove international materials markets. Today, that narrative has shifted. New housing construction in China is currently navigating the heavy impact of an oversupply in smaller, Tier 3 and Tier 4 cities. Coupled with highly restrictive lending practices implemented to deflate a looming real estate bubble, the market has seen a notable cooling effect.
However, it would be a mistake for any real estate investment firm to write off the region. To stabilize the sector, the Chinese government has introduced targeted policy support poised to revitalize the housing market. These government-backed housing efforts are intentionally pivoting away from speculative development toward large-scale affordable housing initiatives and ambitious urban renewal projects. This strategic shift is designed to drive sustainable growth in key urban centers, absorbing excess inventory while providing modern living standards.
Beyond China, the wider Asia/Pacific global housing market is thriving on the back of rapid urbanization. From India to Southeast Asia, developers are aggressively building high-density multifamily units. Here, modern high-rise towers in advanced economies stand in stark contrast to informal settlements in emerging nations. Governments across the region are stepping in to formalize and upgrade their housing stock, presenting lucrative opportunities for international property development firms.
North America: The Single-Family Resurgence and the Sun Belt Boom
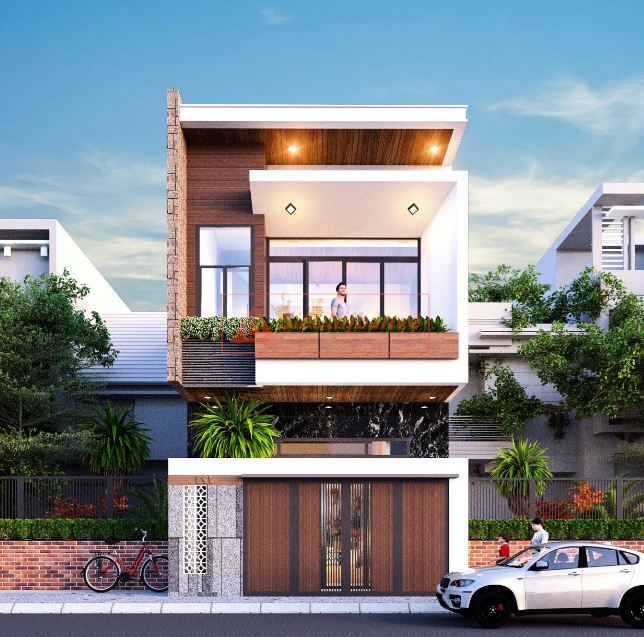
Shifting our focus to the West, the North American sector of the global housing market is experiencing its own unique evolution. If you are looking at the US housing market, the overarching theme is a distinct pivot toward single-family homes, particularly in lower-density environments.
Multifamily developers in high-density urban cores are currently facing a triad of headwinds: compressed profit margins, high vacancy rates in certain metro areas, and the heavy burden of elevated mortgage rates. As a result, the upfront capital requirements and long project timelines of urban high-rises are making them less attractive.
Conversely, single-family builds are surging. Aging millennials have firmly entered their peak homebuying years. Despite economic friction, improving income conditions among this demographic are supporting incremental, sustained growth in single-family demand. This is overwhelmingly evident in the Sun Belt and exurban areas. Local search intent for real estate investment in these regions is off the charts. We are seeing massive capital inflows into the Texas real estate development sector (specifically around Dallas and Austin), as well as the Florida housing market, with Miami remaining a hotspot for both domestic and international buyers.
In these lower-cost regions, land is more readily available, allowing developers to execute faster turnarounds. Furthermore, older housing stock built before 1980 still dominates the North American landscape, driving immense demand for home equity loans and mortgage refinancing as homeowners seek to upgrade their properties for better energy efficiency and modern smart-home technology.
Western Europe: Urban Density and the Green Real Estate Investment Wave
In Western Europe, the global housing market is dictated by two primary forces: acute land scarcity and aggressive environmental regulations. Demand for energy-efficient and low-carbon housing is completely reshaping new construction. Driven by strict EU climate goals and stringent new building codes, consumer preference has firmly aligned with sustainable living environments.
Because sprawling suburban development is largely unfeasible in Western Europe, urban infill and redevelopment projects are gaining massive traction. Cities are aggressively seeking to increase housing density near transit corridors, revitalized industrial zones, and major employment centers. For those involved in wealth management and real estate investment, Western Europe offers a highly stable, albeit heavily regulated, environment. The housing stock here is characterized by high-density rental housing and multifamily units.
To modernize this aging landscape, developers are leaning heavily into modular solutions and advanced property management services. The integration of PropTech (Property Technology) is essential here, allowing landlords and property managers to optimize energy consumption and comply with strict carbon-emission caps.
Central and South America: The Middle-Class Expansion
Looking at Central and South America, the global housing market is being propelled by steady internal migration and a determined expansion of the middle class. Historically, much of the housing stock in this region has been informal or self-built, which inherently struggles with major infrastructure deficits and extreme vulnerability to climate change.
Today, new housing projects in Latin America are increasingly focused on climate resilience and affordability. We are seeing a distinct rise in the development of flood-resilient units and planned communities. Government subsidies and strategic partnerships with private real estate development firms are actively working to reduce massive housing deficits. This region represents a high-growth frontier for investors who are willing to navigate emerging market dynamics, offering substantial returns for those who bring structured property management and scalable construction technologies to the table.
Eastern Europe: Navigating Demographic Nuance
The Eastern European segment of the global housing market presents a highly complex, yet fascinating, puzzle. This region is currently facing significant constraints, primarily driven by high inflation, severe labor shortages, and generally weak consumer confidence. Furthermore, the region is dealing with the legacy of Soviet-era housing blocks.
This aging infrastructure presents massive renovation needs. However, the revitalization of this housing stock is complicated by highly fragmented ownership structures and a broader trend of demographic decline in certain countries. Despite these headwinds, there is a silver lining for the global housing market here. Niche opportunities are arising in the modernization of these existing residential floor spaces. Energy retrofits, funded in part by European subsidies, are creating a consistent pipeline of work for specialized construction and property management firms.
Africa and the Middle East: The Next Frontier of Real Estate Development
If you want to see where the sheer volume of the global housing market is heading over the next two decades, look to Africa and the Middle East. Surging population growth and unprecedented urban expansion are fueling incredibly strong demand. By 2035, the volume of new residential floor space required in these regions will be staggering.
In the Middle East, high-CPC sectors like commercial real estate and luxury residential development continue to attract massive foreign direct investment. However, the broader regional trend is heavily influenced by climate. New construction methods are prioritizing heat-ready designs and water-efficient infrastructure.
Meanwhile, across the African continent, large-scale affordable housing initiatives are rapidly taking root. Governments are acutely aware that to stabilize their growing economies, they must provide access to decent, formal shelter. This is driving a massive influx of master-planned communities and low-cost, high-yield multifamily housing projects. For the seasoned expert in real estate investment, Africa represents the ultimate long-term play in the global housing market.
The Data: Floor Space, Housing Stock, and the 2035 Outlook
When we evaluate the quantitative data driving the global housing market—spanning historical trends from 2015 to our 2035 forecasts—the shift in existing and new residential floor space is telling. Globally, single-family housing stock continues to hold the lion’s share of total square meterage, heavily weighted by North America and parts of Oceania. However, the volume of new multifamily housing units being brought to market is accelerating at a much faster pace globally, driven by Asia, Europe, and Africa.
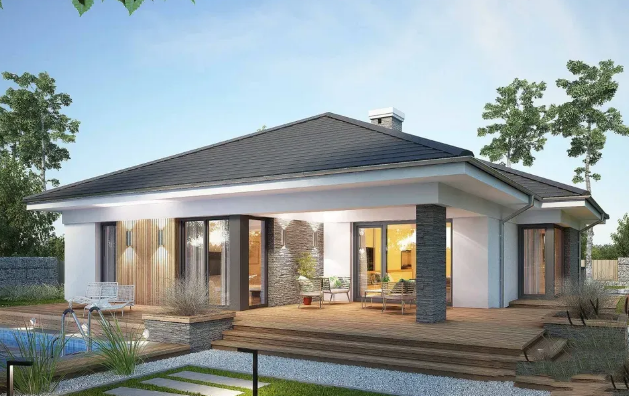
This divergence in the global housing market means that capital allocation must be highly strategic. You cannot apply a North American single-family investment model to a Western European or Asian market and expect success. Furthermore, the convergence of private housing (both owner-occupied and rental) and public/social housing initiatives means that public-private partnerships (PPPs) will become a dominant financial vehicle in the global housing market over the next decade.
The Future is Resilient, Efficient, and Inclusive
Even as regional sectors of the global housing market diverge in their specific pacing and structural preferences, they are ultimately united by common themes. There is an urgent, undeniable need across the globe for resilient, highly efficient, and inclusive housing stock. Whether it is a modular single-family home in the American Sun Belt, a retrofitted low-carbon apartment in Berlin, or a newly formalized affordable housing unit in Nairobi, the core objective remains the same: accommodating rapidly changing social and environmental realities.
The global housing market has evolved from a disjointed collection of localized builder networks into a highly sophisticated, technology-driven global asset class. Those who recognize the value of off-site construction, the necessity of energy-efficient design, and the shifting demographic tides will be the ones who dominate the next decade of real estate.
If you are looking to position your portfolio ahead of these macroeconomic shifts, or if you need to optimize your current assets using the latest in property management and real estate investment strategies, the time to act is now. Reach out to our advisory team today to schedule a comprehensive portfolio review, and let’s ensure your real estate strategy is built to capitalize on the 2025 global housing market evolution.